

Do You Need a Financial License to Launch a Fintech Platform?
Do You Need a Financial License to Launch a Fintech Platform?
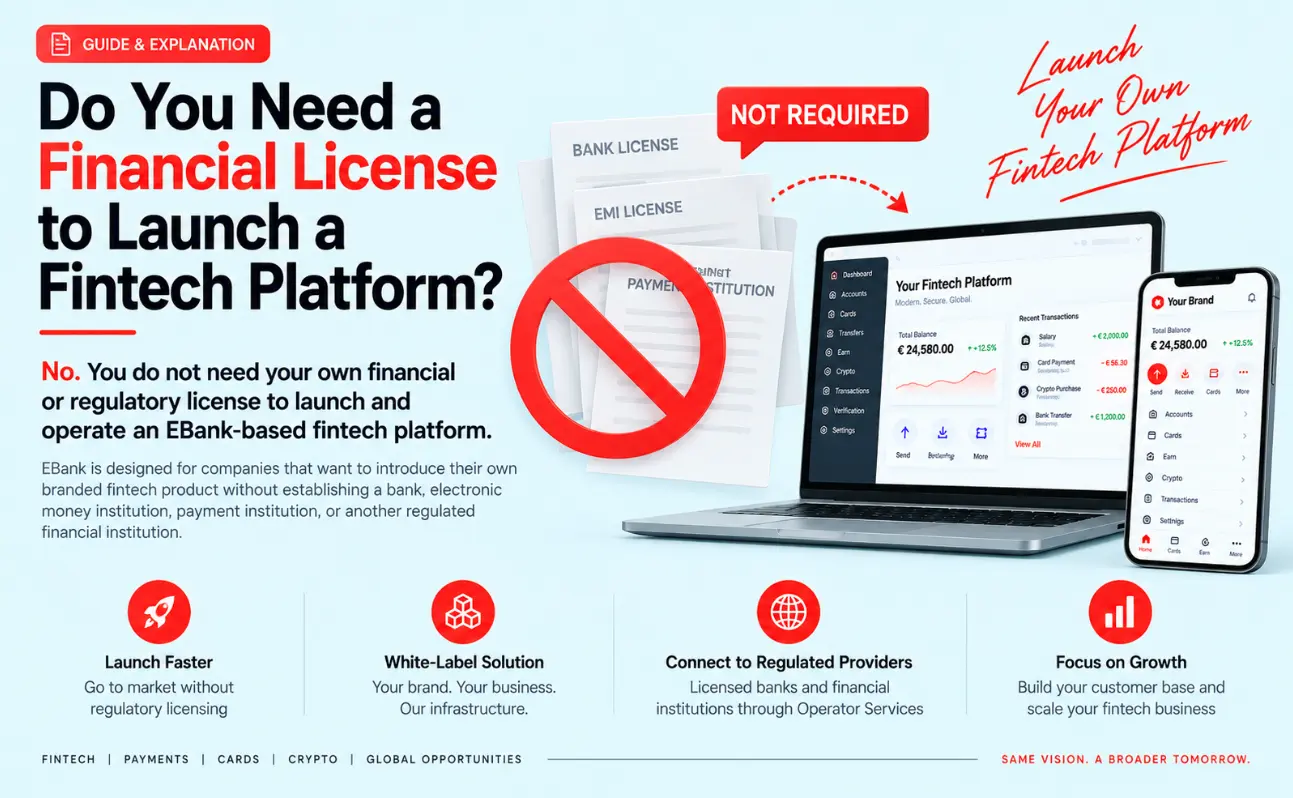
No. You do not need your own financial or regulatory license to launch and operate an EBank-based fintech platform. EBank is designed for companies that want to introduce their own branded fintech product without establishing a bank, electronic money institution, payment institution, or another regulated financial institution.
The EBank model separates the technology and commercial role of the operator from the regulated financial activities performed by licensed providers. Your company operates its own branded platform, manages its customer proposition and sets its fees, while regulated services are delivered through licensed financial institutions and providers connected via Operator Services.
In this guide, we explain how the model works, where EBank and Operator Services fit into the structure, and what an operator must complete before launching.
You Launch a Fintech Product — Not a Bank
Your company can own and operate a branded financial technology platform without holding its own banking, EMI, PI, MSB, MiCA, or other financial license. Customers use the approved services through your brand, domain, and interface, while the regulated components are provided through licensed third parties.
The roles are clearly separated:
Purchasing and operating EBank does not make your company a bank. It allows your company to launch its own branded fintech product within a regulated provider framework.
No Own Regulatory License Is Required
Operators using EBank with Operator Services do not need to obtain their own financial or regulatory license. The model is specifically structured so that the operator provides the branded customer experience and commercial service, while regulated financial functions are performed through connected licensed providers.
Under this structure, the operator does not independently:
These functions are performed by licensed providers after the operator completes KYB and its business model, website, target countries, customer types, and expected activity have been approved.
KYB is not an application for your own financial license. It is the provider's compliance review confirming that your company can use the connected infrastructure within the approved operating model.
Why Operator Services Is Essential
An EBank software license gives you access to the white-label technology. Operator Services provides the regulated connectivity required to activate supported financial functionality.
Depending on the selected plan, approved jurisdiction, provider availability, and customer eligibility, Operator Services can connect the platform to:
The operator does not need to build separate direct integrations with every bank or financial provider. The required services are connected to EBank through Operator Services.
How the EBank Model Works
EBank is deployed under the operator's own approved brand and domain. Customers interact with the operator's platform, while regulated services are delivered through the connected provider infrastructure.
The launch process consists of the following steps:
- Activate the EBank license. The operator selects the appropriate license and completes payment through its ATNM account.
- Configure the platform. ATNM deploys EBank under the operator's brand, domain, logo, colors, settings, and approved modules.
- Activate Operator Services. Operator Services is included in the Commercial License and can be added separately to the Regular monthly license.
- Complete operator KYB. The operator submits its corporate, ownership, website, market, customer, and transaction information.
- Receive provider approval. The provider reviews the application according to its compliance rules and risk appetite.
- Connect financial services. Approved accounts, transfers, cards, verification, and other functions are activated through the relevant APIs.
- Launch the branded product. The operator begins serving approved customer categories and markets through its own platform.
The standard EBank deployment takes approximately seven days after payment and receipt of the required materials. Standard EU Operator Services onboarding can take up to 20 business days. Provider approval cannot be guaranteed.
What the Operator Controls
The operator remains the owner of its business and customer-facing product. EBank provides the infrastructure needed to control the commercial experience without requiring the operator to become a regulated financial institution.
Own Brand and Domain
The platform is presented under the operator's approved name, logo, colors, domain, and customer-facing identity.
Customer Relationships
The operator develops its customer base, communicates with users, and provides first-line commercial support.
Fees and Markups
The operator can configure its own customer fees and markups while accounting for provider tariffs.
Platform Management
The administration panel provides tools for managing users, services, transactions, limits, verification, and operations.
What the Licensed Providers Handle
The connected providers perform the financial activities that require regulatory permissions. Depending on the approved configuration, their responsibilities can include:
The exact provider, jurisdiction, terms, availability, and division of responsibilities depend on the approved program and are disclosed within the applicable operating structure after activation.
KYB Approval Is Required — A Financial License Is Not
Every operator must successfully complete KYB before regulated services can be activated. Providers must understand who owns and controls the company, what the platform offers, where it will operate, which customers it will serve, and what activity is expected.
The KYB review may include:
Passing KYB authorizes the operator to access approved provider services through Operator Services. It does not issue a separate financial license to the operator, because such a license is not required within this model.
Who Holds the Customer's Funds?
Customer funds are not held by ATNM Digital Solutions or by the operator. They are held or safeguarded through licensed financial institutions within the connected provider infrastructure, according to the applicable program and regulatory requirements.
End customers can receive dedicated virtual IBANs in their legal names where supported and approved. The available account structure, currency, IBAN jurisdiction, payment rails, and safeguarding arrangement depend on the relevant provider and market.
Can You Use the Word "Bank" in Your Brand?
No. Because the operator is launching a fintech platform and is not itself a licensed bank, the platform name, logo, website, and marketing materials must not present the operator as a bank or use misleading regulatory claims.
The operator should select an original fintech, payment, wallet, or financial-services brand that corresponds to its domain. The roles of the operator and connected providers must be presented through the required website disclosures.
EBank is the name of the software product supplied by ATNM Digital Solutions. It does not mean that the company operating the platform becomes a bank.
Supported Markets and Services
No own license is required, but individual services are still subject to provider availability, supported markets, compliance controls, and approval.
Review the current Supported Markets page to confirm that your intended countries, customers, and services fit the available provider framework.
Frequently Asked Questions
Do I need my own financial or regulatory license?
No. Operators do not need their own banking, EMI, PI, MSB, MiCA, or other financial license to launch and operate an EBank-based fintech platform.
Why is a license not required?
The operator manages the branded technology platform, while regulated services are performed through licensed providers connected by Operator Services.
Does an EBank license make my company a bank?
No. It provides access to white-label software. It does not turn the operator into a bank or issue a regulatory authorization.
Do I still need to complete KYB?
Yes. KYB is mandatory for access to provider services. It verifies the company and business model but is not an application for the operator's own license.
Is provider approval automatic?
No. Each provider makes its own decision based on the operator, business model, website, markets, customers, and expected activity.
Who holds customer funds?
Funds are held or safeguarded through licensed financial institutions within the approved provider structure, not by ATNM or the operator.
Can I set my own customer fees?
Yes. The operator can configure its own fees and markups while accounting for underlying provider tariffs.
Can I serve customers worldwide?
No. Countries, customer categories, products, and rails remain subject to supported-market rules, sanctions requirements, and provider approval.
Launch Without Your Own Regulatory License
You do not need your own financial or regulatory license to launch a fintech platform with EBank.
The EBank and Operator Services model is designed for companies that want to launch their own branded fintech product without establishing a bank, EMI, payment institution, MSB, or another regulated financial institution.
ATNM provides the technology and provider connectivity. The operator manages its brand, customers, pricing, and business. Licensed providers deliver the regulated financial services, compliance infrastructure, payment rails, accounts, and card functionality included in the approved program.
The operator must complete KYB and work within supported markets and provider requirements, but it does not need to obtain its own regulatory license.
Launch Your Own Fintech Platform with EBank
Explore the EBank white-label platform, review supported markets and pricing, and prepare your company for Operator Services onboarding.